
A Kenyan-built digital platform that enables businesses to track greenhouse gas emissions and prepare sustainability reports has been launched ahead of new reporting requirements set to take effect in 2027.
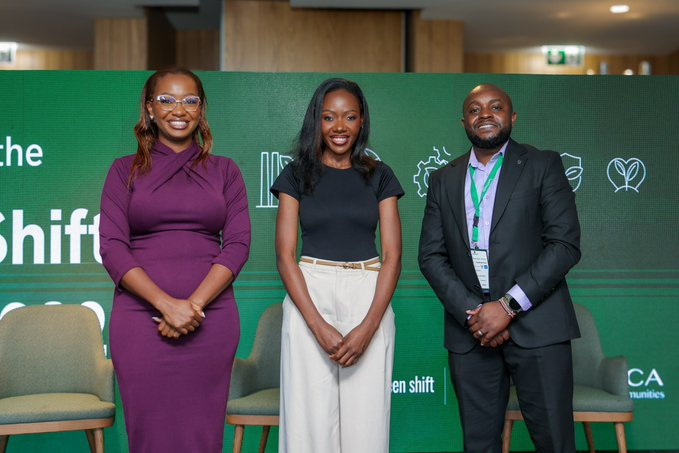
The Ardena Platform, launched by Ardena Consulting at the GreenShift Forum 2026 in Nairobi on October 22, is designed to help businesses collect environmental, social and governance (ESG) data, calculate emissions, monitor performance and prepare disclosures using a single system.
Its launch comes as Kenya’s Institute of Certified Public Accountants (ICPAK) and regulators work to prepare businesses for the adoption of international sustainability disclosure standards, which require organisations to report material sustainability-related risks and, under climate-specific requirements, provide information on greenhouse gas emissions and climate-related risks.
A readiness assessment released in September by the Insurance Regulatory Authority (IRA) found that Kenya’s public-interest entities scored 1.51 out of four on preparedness for the new reporting requirements, indicating that significant gaps remain. The assessment identified weaknesses in climate scenario analysis, greenhouse gas measurement and other sustainability metrics.
Ardena Consulting Chief Executive Officer, Njoki Kamau-Mbugua, noted that the platform combines automated data collection, greenhouse gas calculations, performance dashboards and reporting tools intended to reduce the time businesses spend compiling sustainability information.
Its emissions calculator covers Scope 1, Scope 2 and Scope 3 emissions. These refer respectively to direct emissions from sources a company owns or controls, indirect emissions associated with purchased energy, and other indirect emissions across its value chain, including suppliers and product use.
“This information can help businesses establish emissions baselines, identify major sources of pollution and track progress towards reduction targets. Companies can use the findings to assess options such as improving energy efficiency, switching to cleaner energy, reducing fuel consumption and engaging suppliers to lower value-chain emissions,” said Stephanie Ojee, Ardena’s Chief Operating Officer
Ardena says the system can collect data from operational systems, utility providers, human resource platforms and supply chain partners. Built-in validation is intended to flag anomalies before information is incorporated into reports.
The platform also offers mobile data collection for field teams working in low-connectivity areas, a feature that could support data gathering from agricultural operations, remote project sites and suppliers that lack sophisticated digital systems.
Other functions include dashboards for sustainability managers and board committees, automated tracking of reporting deadlines, and an audit trail that records and attributes data entries. The company says these functions can reduce reporting time by up to 70 per cent.
Kenya is moving towards a more structured system for sustainability disclosures, increasing pressure on organisations to establish reliable processes for measuring and reporting environmental performance.
Under the country’s phased adoption of the International Financial Reporting Standards Foundation’s sustainability disclosure standards, IFRS S1 and IFRS S2, public-interest entities are due to begin mandatory application for reporting periods starting January 1, 2027. Large non-public-interest entities follow in 2028, while small and medium-sized entities are scheduled for 2029.
IFRS S1 sets general requirements for disclosing material sustainability-related risks and opportunities that could affect an organisation’s prospects. IFRS S2 focuses specifically on climate-related disclosures, including governance, strategy, risk management, emissions metrics and targets.
For companies, this means sustainability reporting increasingly requires documented processes and consistent data rather than broad statements about environmental responsibility.
The regulatory transition also matters for access to finance. Banks and development finance institutions may need credible information to assess climate-related risks and the environmental performance of projects they finance. Businesses seeking investment or supplying multinational companies may face additional requests for emissions and sustainability data.
According to Ardena CEO, the platform is designed to map one dataset against several reporting frameworks, including the Global Reporting Initiative Standards, the Sustainability Accounting Standards Board Standards, the Task Force on Climate-related Financial Disclosures, the International Finance Corporation’s Performance Standards and disclosures associated with Kenya’s Capital Markets Authority (CMA).
“This could reduce the duplication that occurs when organisations prepare different reports from the same underlying information. The platform also includes deadline tracking for requirements associated with the CMA, the Central Bank of Kenya, the Nairobi Securities Exchange and international lenders.
The broader environmental significance of such systems lies in their potential to connect reporting with operational decisions. For instance, a company that measures electricity consumption alongside its emissions can identify energy-intensive operations and assess whether efficiency measures are reducing its carbon footprint. Monitoring water use and waste generation can reveal opportunities to conserve resources, reduce pollution and improve production processes.
Consistent supplier data can also help organisations identify environmental risks beyond their immediate premises, including emissions and resource use in their supply chains.
Ardena says the platform includes audit trails and version control to support accountability and external assurance to help establish where information came from and who supplied it.